➤ Are Anthem HMOs continuing?
In most areas, yes. Anthem’s parent company Elevance is offering 308 Medicare Advantage plans for 2027, down from 345, and pulling plans from 56 counties. If you have an Anthem HMO, check your Annual Notice of Change or non-renewal letter to confirm your plan continues.
➤ Is Anthem leaving South Carolina?
Yes. Elevance, Anthem’s parent company, is exiting Medicare Advantage in South Carolina for 2027. Members will receive a non-renewal notice, stay covered through December 31, 2026, and can choose a new plan or use their guaranteed issue right to buy certain Medigap plans.
➤ When can I enroll in an Anthem Medicare Advantage plan for 2027?
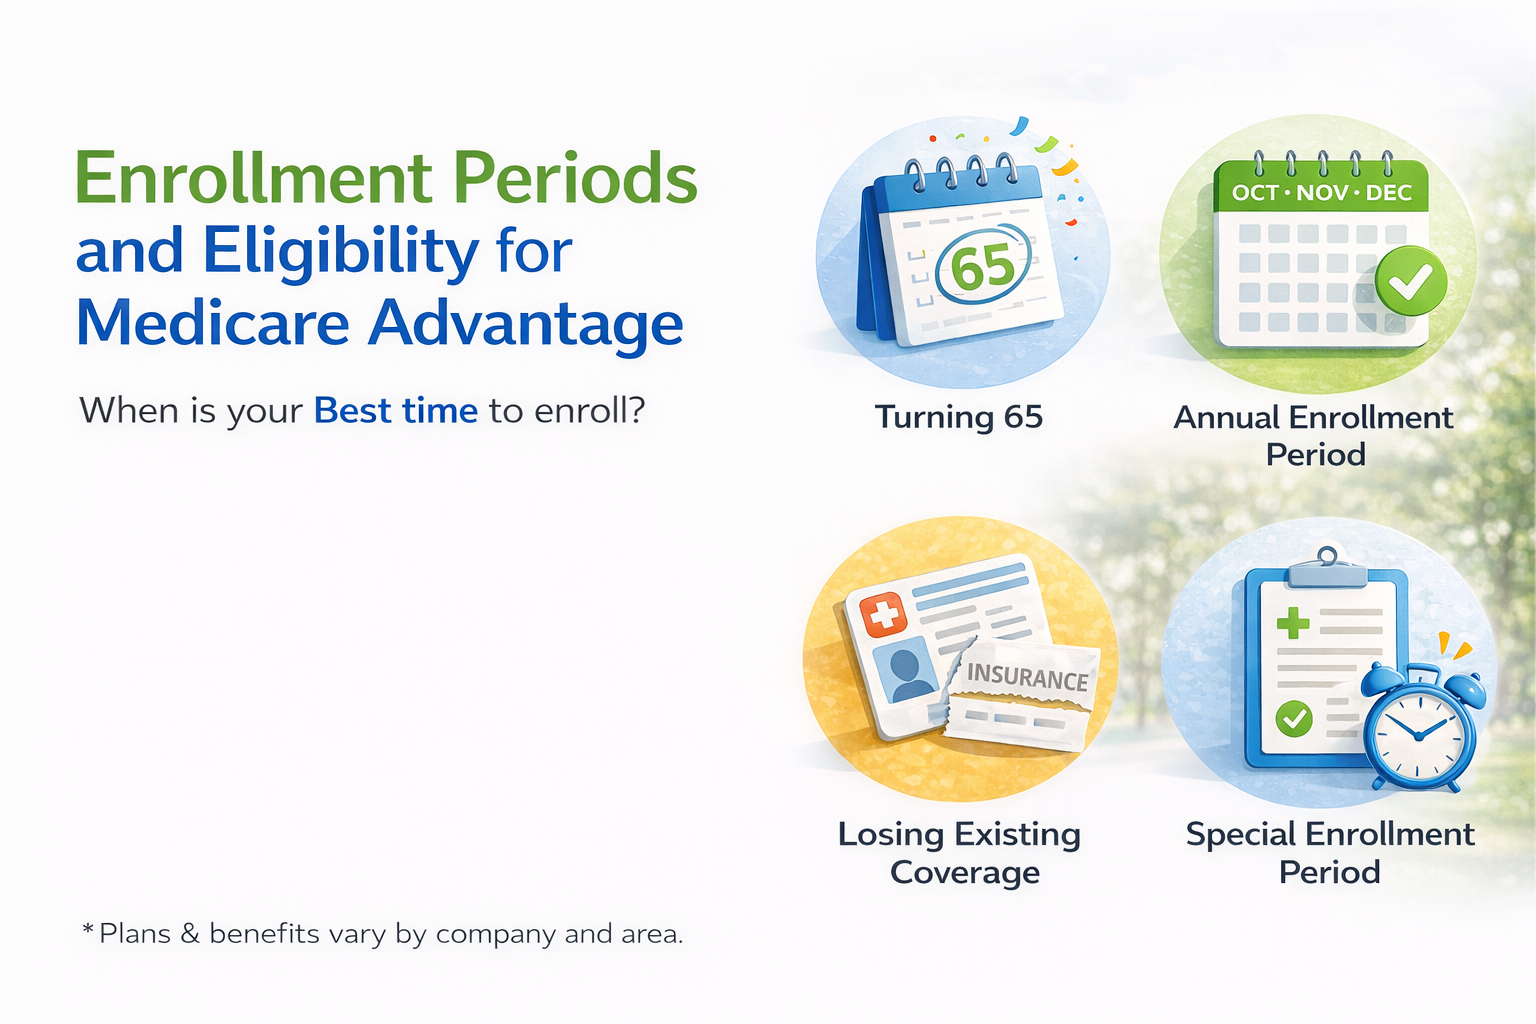
You can enroll in an Anthem Medicare Advantage plan for 2027 during Annual Enrollment, October 15 to December 7, 2026, with coverage starting January 1, 2027. If you are already in Medicare Advantage, you can also make one change from January 1 to March 31, 2027.
➤ What happens if my Medicare Advantage plan is ending?
Your plan will send a non-renewal notice, and your Anthem coverage continues through December 31, 2026. You can choose a new plan during Annual Enrollment or a Special Enrollment Period, and you generally have a guaranteed issue right to buy certain Medigap plans without health questions.
➤ Is Anthem adding Special Needs Plans for 2027?
Yes. Elevance is expanding its Chronic Condition Special Needs Plans, or C-SNPs, into Colorado and Maine for 2027. These plans are limited to people with qualifying chronic conditions, so check your eligibility and whether one is offered in your county.
➤ What brands does Anthem use for Medicare Advantage?
Anthem’s parent company Elevance sells Medicare Advantage plans under several brands, including Anthem, Wellpoint, Freedom Health, Optimum HealthCare and Simply. The brand you see depends on your state, so check your plan documents to confirm which company issues your coverage.
➤ How does an Anthem HMO work?
An Anthem Medicare Advantage HMO generally requires you to use in-network doctors and hospitals except for emergencies and urgent care, and you may need referrals to see specialists. HMOs often have lower costs than PPOs, so confirm your doctors are in network before you enroll.